So… you’re thinking about moving to Harrison, Ohio in 2026?You’re not the only one. More and more buyers are searching for “homes for sale in Harrison OH” and &ldquo

Dated: September 18 2025
Views: 27
If you’ve been watching the headlines lately, you probably saw: the Fed just cut its key interest rate for the first time in 2025. But what does that really mean for people thinking about buying a home, refinancing, or just trying to make sense of how this affects everyday money stuff? Let’s unpack it.
On September 17, 2025, the Federal Reserve reduced its benchmark (or “federal funds”) rate by 25 basis points (i.e. 0.25%) to a range of 4.00% to 4.25%. The Guardian+3Investopedia+3Federal Reserve+3
It’s the Fed’s first rate cut since December 2024. Investopedia+1
The move is part of a shift in focus: more concern now about a slowing job market and rising risk in employment, while inflation remains above target but is being watched carefully. Federal Reserve+2Investopedia+2
Before diving into how the Fed’s decision affects mortgages, a few basics:
The Fed doesn’t directly set long-term mortgage rates. But its decisions influence the broader interest rate environment. AP News+2Scotsman Guide+2
Mortgage rates tend to follow yields on government bonds (especially the 10-year Treasury note) and the behavior of mortgage‐backed securities. If bond yields go up, mortgage rates usually go up, and vice versa. AP News+1
Expectations matter. When people expect more Fed rate cuts, or see economic weakening, bond yields often adjust ahead of time. That means mortgage rates might already reflect anticipated Fed moves. AP News+2Scotsman Guide+2
Here are the likely effects, and what to watch out for:
| Scenario | What tends to happen |
|---|---|
| Fixed-rate mortgages (30-year, 15-year) | These rates can drift down following a Fed cut—but not immediately or always by much. Because fixed mortgages are tied more to long-term bond yields than short-term Fed rates, any drop depends on how much long-term yields fall. Scotsman Guide+2AP News+2 |
| Adjustable-rate mortgages (ARMs) | More likely to see direct benefit sooner. ARMs often adjust based on short-term rates or indexes influenced by Fed policy. If the Fed cut lowers the relevant benchmark, payments can drop. Fox Business+1 |
| Refinancing | A rate drop gives refi hopefuls something to chew on—if the rates drop enough to overcome closing and refinancing costs, then refinancing can make sense. Even modest drops might be enough, depending on how long you plan to stay in the home. CBS News+1 |
Upside:
Potentially lower monthly payments (especially for ARM holders or for those refinancing).
Better affordability, which might get more people off the fence and into homes.
A sign that the Fed sees some risk in slowing growth/employment, so it’s trying to be proactive.
Caveats:
Inflation is still high; if inflation doesn’t come down, bond investors may demand higher yields to offset risk. That could push mortgage rates up even if the Fed cuts short-term rates. AP News+2Scotsman Guide+2
Many lenders likely already priced in this Fed cut. So the “news” might already be baked into current mortgage rates. That means you might not see a jump downward immediately. CBS News+2AP News+2
Other forces like supply/demand in housing, credit spreads, bond market reactions, and global economic developments will also play big roles.
If you’re in the market (or considering refinancing), here are some steps:
Shop around. Different lenders respond at different speeds. One lender might pass on rate improvements faster than another.
Lock in a rate if you see one you like, especially if predictions are for further cuts but with uncertainty. A good rate lock can protect you if rates bounce back up.
Calculate whether refinancing makes sense. Even if your current rate is decent, check if you can reduce your payment enough (after costs) to make it worthwhile.
Keep an eye on inflation data and economic indicators. If inflation surprises to the upside (goes up more than expected), mortgage rates might creep up even in the face of cuts.
The Fed’s 0.25% rate cut to 4.00–4.25% is a meaningful move—it signals concern about slowing job growth and economic risks. For mortgage interest rates, it’s a good sign, but it’s not a guarantee of big drops overnight. Fixed mortgage rates may ease, but ARMs/refinancings are likelier to feel the effects faster. If you're thinking about buying or refinancing, this moment could offer some opportunity—just go in with your eyes open.
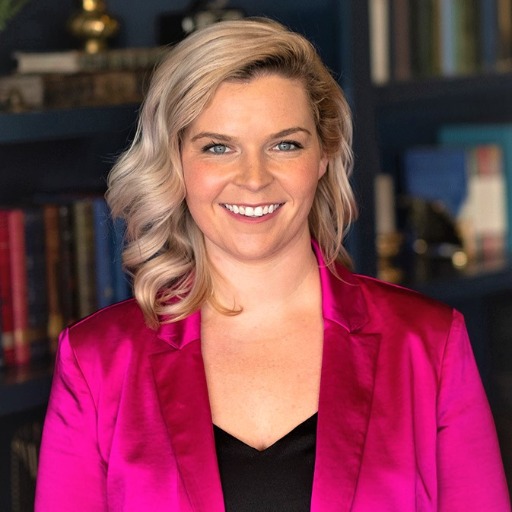
This career quickly turned into a passion for helping others achieve their goals of homeownership. And proving to myself that sometimes you just need to take a terrifying leap into the unknown to real....
So… you’re thinking about moving to Harrison, Ohio in 2026?You’re not the only one. More and more buyers are searching for “homes for sale in Harrison OH” and &ldquo
Why the Spring Real Estate Market Starts Now (And How Cincinnati + Northern Kentucky Sellers Win)If you’re thinking, “I’ll wait until spring to sell my home…” —
Hi, I’m Robyn — but most people know me as The Realtor Robyn.I didn’t get into real estate because I dreamed of paperwork, contracts, or lockboxes. I got into it because I needed a
Why Homes in Harrison & Cincinnati’s West Side Are Selling Faster Than You ThinkIf you’re a move-up buyer keeping an eye on Harrison and the West Side of Cincinnati, you may be
 Copyright © MFRMLS.com All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information on this site was last updated Last updated on September 27, 2026 6:11 PM UTC The listing information on this page last changed on Last updated on September 27, 2026 6:11 PM UTCd. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of MFR MLS.
All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Updated on September 27, 2026 6:11 PM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
 © 2026 Dayton Area Board of Realtors. All rights reserved. Information deemed to be reliable but not guaranteed. The data relating to real estate for sale on this website comes from Dayton Area Board of Realtors and the Broker Reciprocity Program.sm. Real estate listings held by brokerage firms other than Pivot Realty Group are marked with the BR logo and detailed information about them includes the name of the listing brokers. Listing broker has attempted to offer accurate data, but buyers are
advised to confirm all items. Information last updated on September 27, 2026 6:17 PM UTC
Show More...
 Data last updated: September 27, 2026 6:06 PM UTC and updating occurs daily
The data relating to real estate for sale on this web site comes in part from the Internet Data Exchange Program of the ImagineMLS. Real estate listings held by IDX Brokerage firms other than Pivot Realty Group are marked with the IDX logo or the IDX thumbnail logo and detailed information about them includes the name of the listing IDX Brokers. Information Deemed Reliable but Not Guaranteed. © 2026 ImagineMLS.
All rights reserved.
Show More...
 The data relating to real estate for sale on this web site comes in part from the Internet Data Exchange Program of Metro Search, Inc. Real estate listings held by brokerage firms other than Pivot Realty Group are marked with the Internet Data Exchange logo or the Internet Data Exchange thumbnail logo and detailed information about each listing includes the name of the listing broker.
© 2026 Metro Search, Inc.
 The data relating to real estate for sale on this web site comes
in part from the Broker Reciprocity™ program of the Multiple
Listing Service of Greater Cincinnati. Real estate listings held by
brokerage firms other than Pivot Realty Group are marked with the MLS ™ logo
(the small logo to the left) and detailed information about them includes
the name of the listing brokers. The information herein is furnished by the property owner in good faith
but is subject to verification by the purchaser. Neither the MLS, the Broker,
the Agent nor MFM guarantee or warranty the correctness therein.
All information is dated and is subject to change at any time.
This data is up-to-date as of September 27, 2026 6:01 PM UTC.
Copyright 2026, MLS of Greater Cincinnati, Inc. All rights reserved.
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of NKY MLS (last updated September 27, 2026 5:51 PM UTC). Real estate listings held by brokerage firms other than Pivot Realty Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. All rights reserved.
Show More...
 All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change or withdrawl. Neither listing broker(s) nor SE IN BD REALTORS shall be held responsible for typographical errors, misinformation, misprints and shall be held totally harmless.
